In corporate finance and private equity, few mechanisms generate as much interest and debate as the LBO (leveraged buyout). Popularized since the 1980s, it consists of financing the acquisition of a company by combining equity and debt, in order to increase the return on the capital invested.
Discover the private equity funds available to wealth advisers, family offices and private banks.
But the transaction is not just a financial structure. It plays a major role in business succession: an owner can sell their company, a management team can take over the business, or investors can support a development phase. It sits at the crossroads of wealth strategy, risk management and value creation.
Definition and how it works
An LBO is a transaction in which an investor (often a private equity fund) acquires a company by contributing a share of equity and raising a significant amount of debt. The particularity: the debt is repaid from the cash flows generated by the acquired company, through dividends upstreamed to the acquisition structure.
Classic structure
- Creation of an acquisition holding company, owned by the investors.
- Equity contribution (often 20 to 30% of the price).
- Debt put in place (often 70 to 80%).
- Acquisition of the target company by the holding company.
- Gradual repayment from the cash flows distributed by the target.
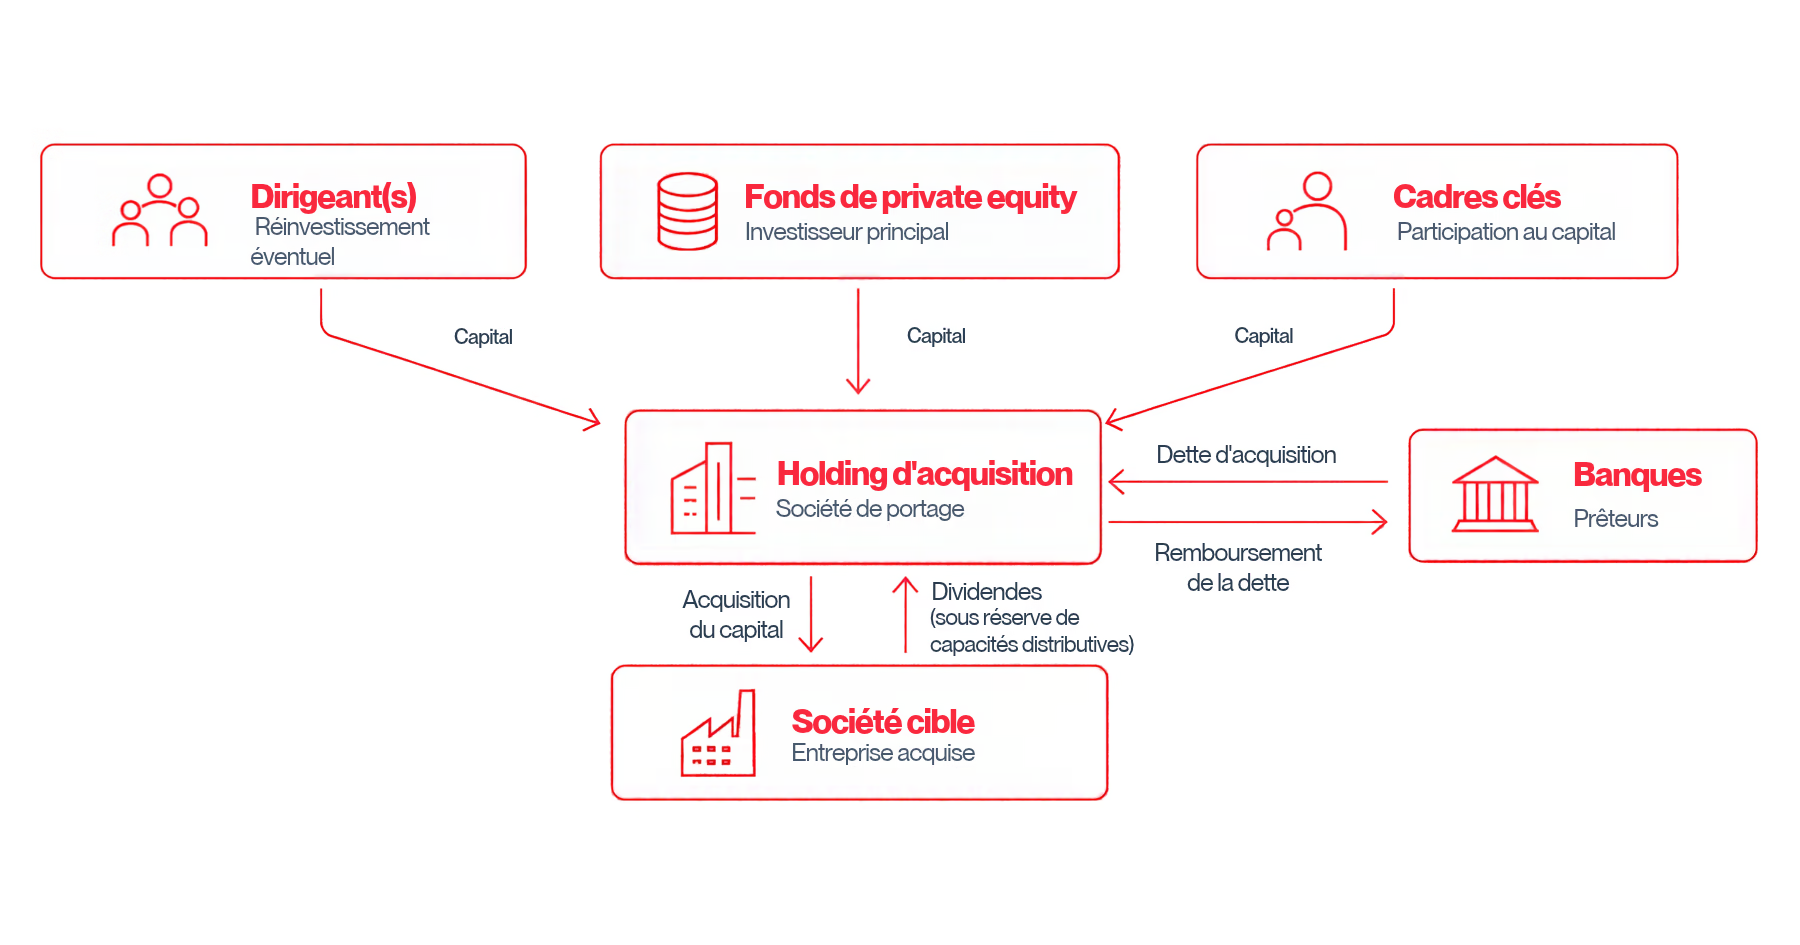
Typical LBO structure: acquisition holding company, equity and debt.
Simplified example
A company is valued at €100m. A fund contributes €25m and borrows €75m. The company generates €20m of annual cash flow distributed to the holding company, which allows the debt to be repaid. If the company is sold for €150m after 5 years, the capital gain on the equity is amplified by the leverage effect.
The LBO therefore rests on a simple principle: using the company's future resources to finance its own acquisition.
Which companies are best suited to this type of transaction?
In practice, a leveraged buyout works best when the target company has favorable characteristics: a mature business, recurring revenues and predictable cash generation. Overly cyclical sectors, or those dependent on an unstable market, make the structure more fragile.
The following criteria are often found:
- regular and relatively resilient cash flows;
- moderate capital expenditure (capex);
- stable margins (or realistic improvement);
- reasonable initial debt;
- strong management and clear governance.
These elements make it easier to put in place sustainable financing and secure repayment capacity within the acquisition structure.
The leverage effect: the engine of returns
The leverage effect increases the return on equity through debt.
- Without leverage: €100,000 invested, +30% on sale → +€30,000 (30% return).
- With leverage: €20,000 invested + €80,000 of debt → after repayment, the gain can represent +150% on the initial equity.
This multiplier effect explains the appeal of these transactions. In return, excessive leverage can weaken the acquired company.
The 3 performance drivers
Beyond financial leverage, performance generally comes from three complementary drivers:
- Deleveraging: over time, debt falls thanks to the cash flows upstreamed from the target company to the holding company, which mechanically increases the share of value attributable to shareholders.
- Operational improvement: revenue growth, higher margins, cost optimization, better capital allocation.
- Change in the valuation multiple at exit: if the market values the company more highly (or if its positioning improves), the multiple can rise, amplifying the sale price.
This framework helps explain why two transactions that look similar on paper can produce very different results: execution and timing are decisive.
Variants and role in business succession
There are several configurations, depending on the succession context:
- MBO (management buyout): takeover by internal managers.
- MBI (management buy-in): takeover by external managers.
- BIMBO: combination of internal and external managers.
- OBO (owner buyout): the owner sells part of the capital while keeping control (often a wealth objective).
- Build-up (LBU): growth through successive acquisitions to create a stronger group.
In all cases, the aim is to ensure continuity of ownership and governance while financing a new growth trajectory.
Key steps of a transaction
- Origination: identifying a target (stable cash flows, growth potential).
- Negotiation: price and terms of the takeover.
- Structuring: balance between debt and equity.
- Due diligence: financial, legal and operational audits.
- Creation of the holding company and acquisition of the target.
- Active management: implementation of a value creation plan.
- Exit: sale to an industrial buyer, resale to another investor (including a “secondary”), or IPO.
The holding period is often around 5 to 7 years, although it varies with the strategy and the economic cycle. The success of an LBO depends as much on the rigor of the financial structure as on the quality of operational support.
Financing: a mix of debt
Financing is generally hybrid:
- Senior debt: the most secure, moderate cost, first in line for repayment.
- Mezzanine debt: riskier, better remunerated, sometimes linked to equity.
- Unitranche: “all-in-one” debt, often used for mid-caps.
- High yield: high-yield bonds, mostly reserved for very large transactions.
Debt and collateral: an often underestimated point
In this type of structure, lenders generally expect collateral. The assets of the target company (and sometimes those of the group) can serve as security, which partially secures the financing. In return, the higher the leverage, the higher the cost of debt can be, because the perceived risk is greater.
Taxation also matters: the deductibility of interest on borrowings can improve net returns (depending on the applicable framework).
Talk to our team about the fund selection suited to your clients.
The stakeholders involved
- Private equity funds: capital, governance, strategic steering.
- Banks / lenders: debt and credit structuring.
- Management: often involved to align interests.
- Financial and legal advisers: securing, structuring and execution.
Frequent use cases: transformation and asset carve-outs
These transactions are not used only to transfer a business: they can also finance a strategic transformation. They are found in particular in a move from a listed to a private company (take-private) or in a carve-out, when an activity is separated from a group to become independent.
Deleveraging does not rely only on operating cash flows: it can also be accelerated by selling non-strategic assets or divesting subsidiaries. Well managed, this approach reduces financial risk and refocuses the company on its core business.
Advantages and risks of the LBO
The advantages
- Potentially high returns thanks to leverage.
- Alignment of interests between investors and managers.
- Financial discipline driven by debt repayment.
- Faster growth through capital, expertise and acquisitions.
- A succession solution for an owner wishing to sell on good terms.
The risks to manage
A powerful succession tool, this type of transaction carries specific risks.
a) Financial risks
- Excessive debt: pressure on cash.
- Default risk if cash flows decline.
- Scissors effect: rising rates combined with an economic slowdown.
b) Operational risks
- Poorly executed strategic plan.
- Internal resistance, complex integrations.
- Dependence on management.
c) Social risks
- Difficult restructurings.
- Deterioration of the social climate if short-term pressure is too strong.
d) Wealth-related risks
- In an OBO, a poorly thought-out structure can lead to a loss of control.
- For private investors: low liquidity and a long horizon.
Value creation and economic impact
Value creation often comes from:
- Organic growth (commercial development, innovation).
- External growth (build-ups).
- Operational optimization (margins, processes, organization).
At the macro level, these transactions can facilitate the succession of family businesses, revitalize mature companies and strengthen competitiveness. Conversely, in case of failure, debt can accelerate difficulties, with a real social impact.
Examples of successes and failures
Successes
Dell (2013): Michael Dell and Silver Lake (with the fund GIC) took Dell off the public markets through a leveraged buyout of around $24.9bn, then the largest LBO since the financial crisis. Once private again, the company relaunched its PC business and accelerated its transformation through acquisitions (including VMware). In April 2021, Dell announced the spin-off of VMware to simplify its capital structure and strengthen its position in hybrid cloud and other growth areas.
Picard Surgelés: several successful transactions, a growth driver. The latest LBO, led by Lion Capital from 2010 for around €1.5bn, accompanied the growth from about 820 to 1,185 stores and from €1.1bn to €1.7bn in revenue, before the sale to Invest Groupe Zouari announced in 2024.
Failures
- TXU Energy (2007): an emblematic bankruptcy, with strong sector volatility. Acquired for around $45bn by KKR, TPG and Goldman Sachs Capital Partners, the group saw electricity prices collapse and filed for bankruptcy in April 2014 with debt of around $40bn.
- Toys’R’Us: a textbook case of value destruction and the disappearance of a brand. Acquired in 2005 by KKR, Bain Capital and Vornado with $1.3bn of equity and around $5bn of debt, the retailer went bankrupt in 2017 and wound down its operations in 2018 (the brand has since been relaunched).
These examples illustrate a key point: everything depends on the strength of the acquired company and on the strategy.
(Sources: SEC and Reuters, 2013; Goodwin, 2024; NPR, 2014; Bloomberg, 2017.)
Place in private equity and wealth management
This mechanism is one of the most representative forms of private equity. For institutions and private investors alike, it can offer diversification and returns, through specialized funds. In a wealth management approach, buyout vehicles make accessible transactions that were once reserved for large institutions, opening up private markets to a wider range of investors.
Conclusion – The LBO, a lever to handle with method
The LBO is much more than a financial structure: it is a succession tool, a lever for value creation and an instrument for transforming companies. Well structured, it allows a takeover to be financed, governance to be professionalized and a growth strategy to be accelerated.
Its effectiveness nevertheless depends on balance: too much debt weakens the target company and can destroy the value being sought. Hence the importance of a prudent structure, rigorous operational execution and steering aligned with the long term.
In a context where business succession remains a major issue, this type of transaction keeps a central place, both for wealth and for the economy.
Our teams support you in selecting and accessing funds.
FAQ – The LBO
What is an LBO in finance?
An LBO (leveraged buyout) is a transaction in which a company is acquired using a significant amount of debt. The debt is then repaid from the cash flows generated by the acquired company, which amplifies the return on the equity invested.
How does a leveraged buyout actually work?
An LBO relies on a holding company that acquires a business by combining equity and debt. The target company's cash flows are then upstreamed to the holding company to repay the debt. Value is created through deleveraging, growth and operational improvement.
What is the difference between an LBO and an MBO?
An LBO refers to the financial mechanism of an acquisition with leverage, while an MBO (management buyout) is a specific case in which the current managers buy their own company, often with the support of financial investors.
What are the main risks of an LBO?
The main risk is excessive debt, which can weaken the company if activity declines. Other risks include operational risk (poor execution of the strategic plan), financial risk (rising interest rates) and human risk (dependence on management).
Who can carry out an LBO?
An LBO is usually carried out by private equity funds, sometimes alongside management. In some cases, business owners or private investors can also initiate this type of transaction, particularly in business succession contexts.