A GP stake means taking an interest in the capital of an asset management firm rather than financing one of its funds. As private markets go through a period of liquidity strain, the strategy is becoming more relevant for GPs and investors alike. This guide sets out how it works, its revenue sources, its benefits and its risks, for wealth advisors, family offices and private banks.
Discover GP stakes and our full range of investments in private markets.
Introduction to GP stakes
Instead of financing the investment vehicles run by General Partners (GPs) directly, some investors choose to take an interest in the capital of the management firms themselves. This approach, known as GP stakes, means betting on the growth and profitability of the investment platform itself rather than only on the funds it creates. It stands in contrast to the traditional logic of Limited Partners (LPs), which focuses on the performance of a given fund rather than on the lasting value of the management firm.
To better understand what private equity is and the central role of management firms in value creation, it helps to master the fundamentals, in particular the interactions between GPs, LPs and investment vehicles.
Born in the United States in the 2000s, the strategy has gradually become institutionalised with the emergence of specialist funds such as Dyal Capital (now Blue Owl) and Petershill (Goldman Sachs). Today, the GP stake is recognised as a strategy in its own right, attracting institutional investors looking for stable income that is differentiated from and uncorrelated with listed markets. To access this type of strategy and private markets more broadly, find out how to invest through a private equity platform dedicated to professional investors.
What is a GP stake?
A GP stake investment means acquiring a minority interest, generally between 10% and 30% of a GP’s capital. This position gives the investor a claim on three major sources of revenue:
- Management fees: regular and predictable income based on assets under management (AUM).
- Carried interest: a share of the capital gains generated by the funds, often set at 20% above a performance threshold.
- Co-investments (balance sheet returns): direct exposure to the GP’s financial commitments in its own funds, often on preferential terms.
For the investor, access to these three sources of revenue sets GP stakes apart from more traditional private equity strategies, which only provide the net performance of the funds.
Key takeaways
- A GP stake is a 10% to 30% minority interest in the capital of an asset management firm.
- It gives a claim on management fees, carried interest and the GP’s co-investments.
A fast-growing market
The rise of GP stakes rests on several structural trends:
- Growth of alternative assets: according to Preqin, global assets are expected to reach nearly $30 trillion by 2029.
- Industry consolidation: mid-sized GPs are looking for strategic partners to finance their expansion and compete with the large global platforms.
- Search for stable income: institutional investors favour recurring cash-flow sources that are weakly correlated with listed markets.
- Recovery in deal activity: according to PitchBook, GP stakes transactions represented $3.4 billion worldwide in 2024, the highest level since the record year of 2021.
North America retains a lead, with multi-billion-dollar vehicles dedicated to the largest managers (CVC, PAI, H.I.G. and others). Europe, for its part, is seeing emerging momentum, with growing interest from players such as AXA IM and GP House.
GP stakes: why the strategy is back in focus
For more than a decade, abundant liquidity supported the growth of private markets. The context has changed: the slowdown in exits and IPOs since 2022 has weighed on distributions to investors. Temporary crisis or private equity coming of age? In its 2026 report, Bain describes an industry that has matured and now faces higher expectations from its investors. The rebound in deals and exits seen in 2025 remained narrow, distributions stayed low and fundraising remains difficult for many GPs.
LPs feel the consequences: without enough cash returned from their older funds, their ability to commit to new vehicles shrinks. GPs are hit in turn: assets held for longer, more demanding fundraising and revenues concentrated on a limited number of funds. In this environment, the financial strength of the manager becomes a selection criterion in its own right, and GP stakes respond by addressing the management firm itself, depending on the transaction either by providing it with capital or by offering liquidity to its partners.
Key takeaways
- The slowdown in exits weighs both on LP distributions and on GPs’ ability to raise new funds.
- A GP stake relates to the capital of the management firm itself, not to that of a fund.
Our team supports you in selecting funds across private assets.
A regenerative value-creation model
The particularity of the GP stake is its ability to generate renewed flows over time. Unlike a secondary portfolio, which naturally runs down as funds reach maturity, the GP’s recurring raising of new funds continuously feeds the economic engine. This “regenerative” logic gives the strategy rare visibility.
The value differential compared with a traditional private equity investment is often referred to as the GP Alpha:
- receiving management fees instead of paying them;
- access to carried interest across several funds and vintages;
- exposure to co-investments, generally with no additional fees;
- potential value of the management firm itself in the event of a sale or IPO.
Benefits generally associated with GP stakes strategies
Benefits for investors
- Diversified returns (fees, carry, valuation).
- Income that is generally stable and not very sensitive to market cycles.
- Privileged access to the GP’s governance and pipeline.
- Complementarity with secondaries (reduction of the J-curve).
Why a GP opens up its capital
- Financing growth: when the proceeds go to the firm, the capital can be used to launch new funds or new strategies, strengthen the balance sheet or stabilise cash, with great flexibility of use.
- Reducing reliance on future carried interest: a GP that mainly counts on future capital gains is exposed to exit cycles. Depending on the structure of the transaction, the sale turns part of that future value into immediate resources, for the firm or for its partners.
- Securing key people: in a people-driven business, a better-distributed shareholding and stable cash make it easier to retain partners and to pass the business on between generations.
- Sending a credibility signal: in a more selective market, LPs scrutinise the strength of the management firm. A capitalised GP can find future fundraising easier.
- Gaining new channels and expertise: the minority investor often brings a distribution network and strategic expertise.
Depending on the structure of the transaction, the proceeds may go to the management firm (a capital increase) or to the partners selling part of their interest. Only the first case directly strengthens the GP’s equity.
Better alignment between GPs and LPs
When the transaction strengthens the management firm’s equity, the manager is better placed to actively manage its existing portfolios and meet its long-term commitments, without being under pressure to distribute at any price. This alignment explains why end investors are also interested in the strategy.
Risks associated with GP stakes strategies
Despite their advantages, GP stakes carry specific risks that need to be managed.
- Dependence on fundraising: GPs’ revenues rest on their ability to raise new funds. A slowdown in fundraising directly affects future flows.
- Concentration on human capital: the value of a GP depends heavily on its key people. The departure of strategic partners can weaken its momentum.
- Limited valuation and liquidity: GP stakes are long-term investments (10-12 years), with no real secondary market, and their valuation rests on assumptions that can be sensitive.
- Regulatory environment and reputation: tighter regulation or a controversy can affect the profitability and image of a GP.
- Risk of capital loss and illiquidity: investing in alternative investment funds (AIFs) carries, in particular, risks of capital loss and illiquidity.
Key takeaways
- A GP’s revenues depend on its ability to raise new funds.
- A GP stake is a long-term investment (10-12 years), with no real secondary market.
- The risk of capital loss and illiquidity applies to all AIFs.
Discover the Blue Owl Capital strategy, available through Private Corner to professional investors.
Conclusion – a hybrid, differentiating strategy
At the crossroads of private equity, private debt and secondaries, GP stakes stand out as a hybrid and differentiating strategy. For GPs, they are a lever for growth, succession and financial strength. For investors, they generally offer “meta” access to the private markets economy, with a unique structural alpha and a rare combination of stability and growth.
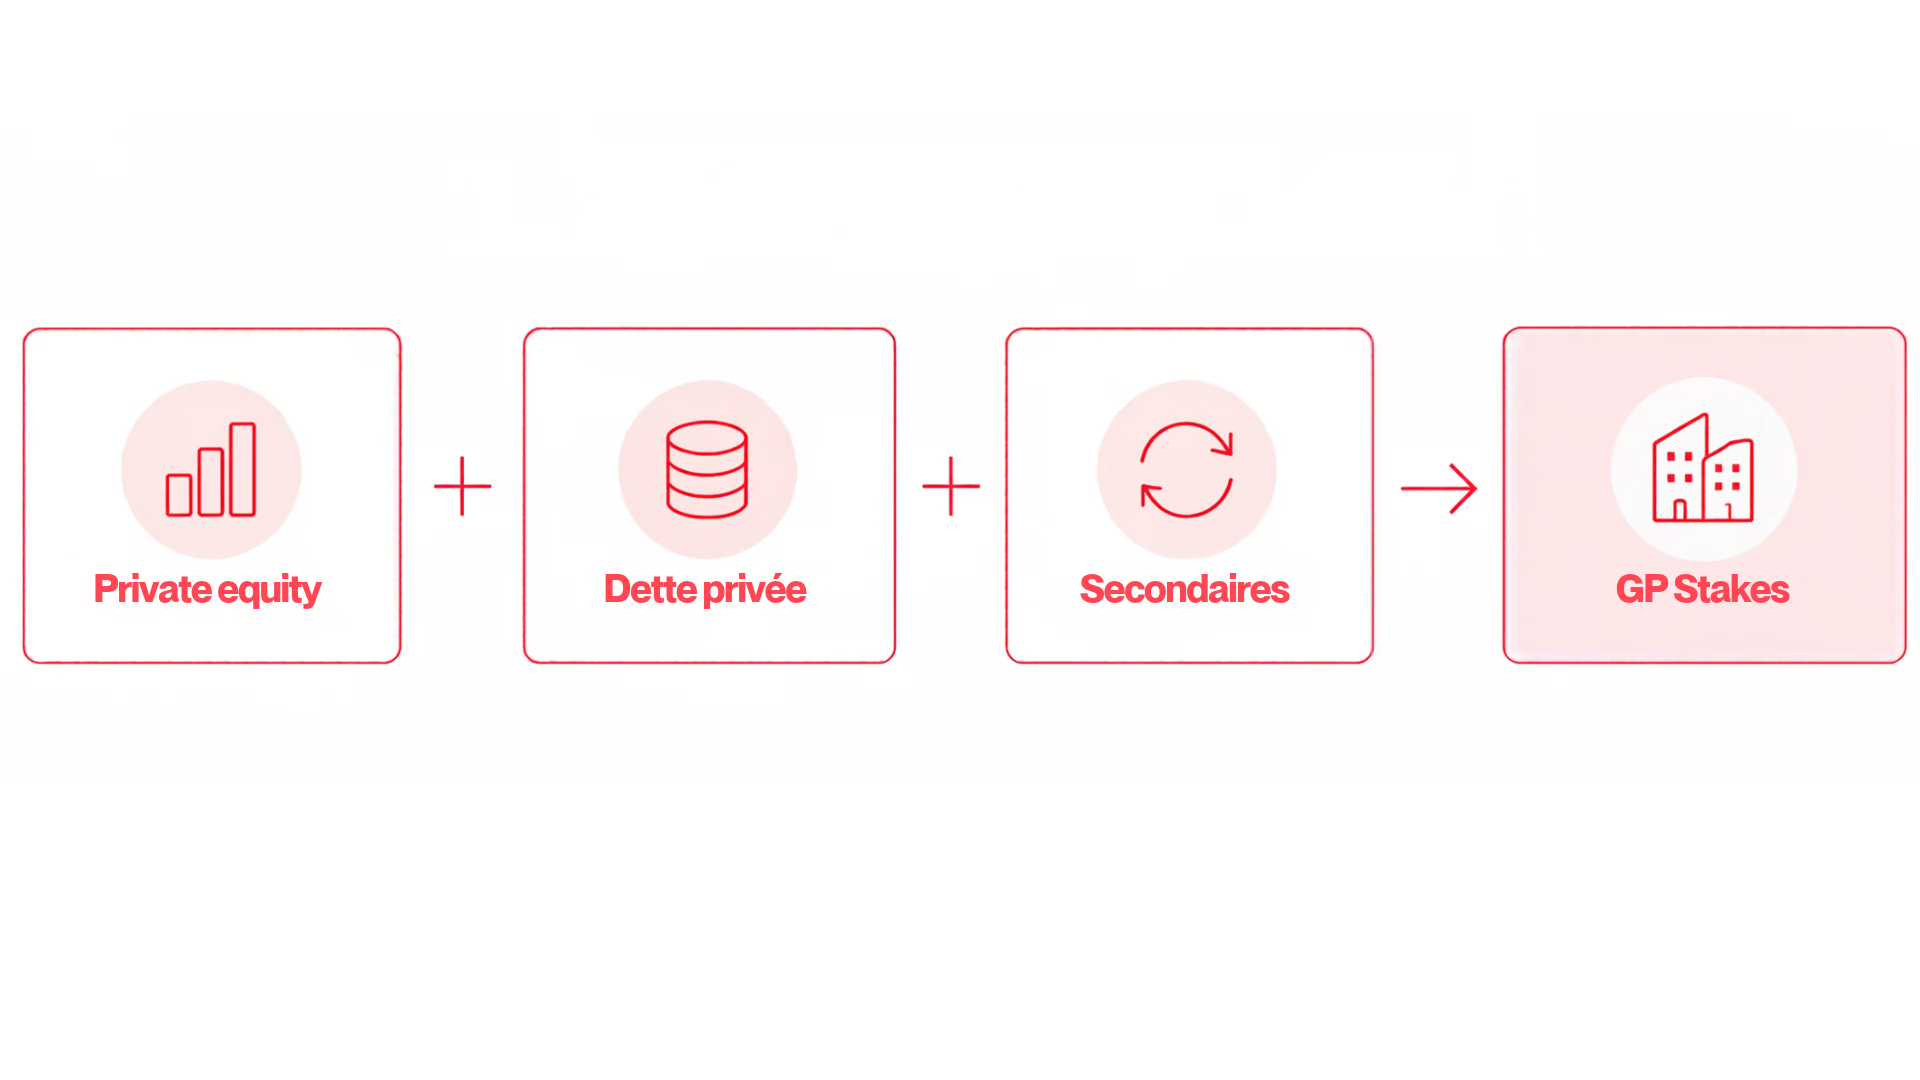
GP stakes, a strategy at the crossroads of several private markets segments.
To access this type of strategy and private markets more broadly, find out how to invest in private equity through a platform dedicated to professional investors.
Access institutional funds through an AMF-licensed platform.
Sources
PitchBook – General Partner Stakes: An Overview (2020); Blue Owl Capital (corporate website).
Investcorp – GP Stakes Investing (2023).
Blue Owl Capital – GP Stakes Strategy Overview.
Preqin – Future of Alternatives 2029 (September 2024): forecast of $29.2 trillion in AUM by 2029.
PitchBook – GP stakes gain traction as fundraising slows (January 2023).
Bain & Company – Global Private Equity Report 2026 (February 2026).
Bennett Jones – The Q4 2025 PE Briefing (January 2026), based on PitchBook data on 2024 GP stakes transactions.
FAQ – GP stakes
What is a GP stake?
A GP stake is a minority interest, generally between 10% and 30%, in an asset management firm (the General Partner, or GP). Depending on the terms of the transaction, the investor can benefit from three sources of revenue: income from management fees, performance fees (carried interest) and returns on the investments made on the GP’s balance sheet (balance sheet returns).
Who are the main players in GP stakes?
The main players in GP stakes include Blue Owl Capital, through its GP Strategic Capital business, Goldman Sachs with Petershill, and Blackstone GP Stakes. These specialist managers invest in private equity management firms and in other private asset classes, notably credit, infrastructure and real estate.
What are the benefits of GP stakes?
GP stakes give exposure to several potential sources of return: recurring income from management fees, performance fees and the appreciation in value of the management firms. When a fund holds stakes in several GPs, it can also offer diversification across strategies, geographies and fund vintages. These benefits remain subject to the performance and risks specific to each investment.
Who invests in GP stakes?
GP stakes investments are mainly made by specialist funds, financed in particular by institutional investors such as pension funds, insurers, sovereign wealth funds and family offices. These strategies may also be available to other eligible investors, depending on the marketing conditions of the vehicles.
Why does a GP sell part of its capital?
A management firm may open up its capital to finance its development, launch new strategies, organise its succession or provide liquidity to its partners. Depending on the structure of the transaction, the capital is either contributed directly to the management firm or paid to the shareholders who sell part of their shares.
Disclaimer: the information presented in this article is provided for information and educational purposes only. It does not constitute investment advice, a personalised recommendation or a solicitation to subscribe to a financial instrument.
Investments in private markets, including GP stakes strategies, carry in particular a risk of capital loss, an illiquidity risk and risks specific to the underlying strategies. Past performance is not a guide to future performance. The funds managed by Private Corner are intended only for professional or equivalent investors.
Before making any investment decision, each investor must read the fund’s regulatory documentation, in particular the Key Information Document (KID) and the fund rules, available from Private Corner, and make sure that the investment is suited to their financial situation, objectives and investment horizon.
Private Corner is a portfolio management company licensed by the AMF on 05/11/2020 under number GP-20000038.